How Rising Home Maintenance Costs Are Changing the Real Cost of Homeownership in America
Anúncios
Buying a home has long been considered an important financial milestone for American families. Homeownership can provide stability, build equity over time, and give households greater control over where they live. However, the financial commitment does not end when the mortgage closes. Maintenance, emergency repairs, insurance premiums, property taxes, and utility bills can significantly increase the actual cost of owning a home.
Across the United States, rising expenses are changing how homeowners approach their budgets, prioritize repairs, and make decisions about moving or renovating. Even households with manageable mortgage payments may face financial pressure when a roof needs replacing, an air conditioning system fails, or insurance premiums increase unexpectedly.
Recent research suggests that homeowners are increasingly concerned about these expenses. Angi’s 2026 State of Home Spending Pulse reported that rising material and labor costs were encouraging households to prioritize essential maintenance and repairs while postponing some discretionary improvements.
Anúncios
This shift has important implications for first-time buyers, longtime homeowners, retirees, and anyone evaluating the financial benefits of purchasing property. Understanding the full cost of homeownership can help families prepare for unexpected expenses and make more informed housing decisions.
In This Comprehensive Guide, Readers Will Learn:
- Why home maintenance costs are becoming a bigger part of household budgets.
- How repairs, insurance, property taxes, and utilities affect the real cost of owning a home.
- Why older homes may require more frequent and expensive maintenance.
- How rising costs are changing renovation and relocation decisions.
- Which expenses prospective buyers should consider before purchasing a property.
- Practical ways to prepare for repairs without sacrificing other financial goals.
- What American homeowners should watch through the rest of 2026.
Why the Real Cost of Homeownership Is Increasing
Mortgage payments are only part of the equation
When prospective buyers calculate whether they can afford a home, they often focus on the purchase price, down payment, mortgage interest rate, and monthly loan payment. These figures are important, but they do not capture every expense associated with owning property.
Anúncios
Homeowners must also account for property taxes, homeowners insurance, utilities, routine maintenance, and repairs. Depending on the property, they may face homeowners association fees, landscaping expenses, pest control, and private road or community charges.
The U.S. Census Bureau reported that median monthly owner costs for American households with a mortgage reached $2,035 in 2024, up from an inflation-adjusted $1,960 in 2023. These figures included selected housing expenses such as mortgage payments, insurance, taxes, utilities, and applicable fees, but did not fully capture maintenance and repair costs.
That distinction matters because a homeowner’s actual monthly housing budget may be considerably higher than the amount shown on a mortgage statement.
A household might have a predictable mortgage payment but still experience significant changes in its overall housing expenses when insurance renews, property taxes rise, or major equipment reaches the end of its useful life.
Maintenance and repair expenses can be unpredictable
Some homeownership costs occur regularly. HVAC servicing, gutter cleaning, lawn care, and routine plumbing inspections can often be scheduled in advance.
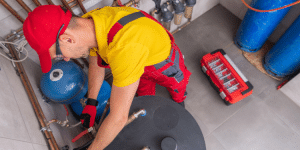
Other expenses are much harder to predict. A leaking roof, broken water heater, damaged foundation, or failed electrical component may require immediate attention, regardless of whether the household has money available.
Angi’s 2025 State of Home Spending Pulse found that 62% of surveyed homeowners were more concerned about affording maintenance than they had been at the end of 2024. The survey also found that 71% had postponed at least one planned home project during 2025.
These findings illustrate how rising expenses can affect decisions even when homeowners continue to maintain their properties. Families may delay cosmetic improvements, reduce discretionary spending, or use savings intended for other goals to cover essential repairs.
The financial challenge is not simply that repairs cost money. It is that several expenses can occur close together, making annual spending difficult to predict.
The Main Expenses Changing the Cost of Owning a Home
1. Labor and building materials
Professional labor and construction materials can represent a substantial share of repair costs. Roofing, plumbing, electrical work, window replacement, and HVAC repairs may require specialized skills, permits, equipment, and materials.
When contractors face higher wages, supply costs, or operating expenses, those increases can be reflected in customer estimates. Homeowners may also encounter scheduling delays when qualified professionals are difficult to find.
The cost of a project depends on the home’s size, location, condition, accessibility, and the complexity of the work. Replacing a few damaged shingles is very different from replacing an entire roof, just as repairing a small plumbing leak differs from replacing corroded pipes throughout a property.
For homeowners, obtaining detailed estimates and understanding what is included in a quote can help prevent unpleasant surprises. It is also important to distinguish necessary repairs from optional upgrades when working with a limited budget.
2. Homeowners insurance premiums
Insurance is another major factor affecting the cost of homeownership. Premiums can rise because of changes in construction costs, regional claims experience, weather-related risks, and insurers’ assessments of future losses.
In some areas, homeowners face particularly significant challenges because of exposure to hurricanes, wildfires, severe storms, or flooding. Some households may have fewer insurance options or need additional coverage to protect against specific risks.
The Federal Reserve’s Economic Well-Being of U.S. Households in 2025, published in May 2026, reported that increases in homeowners insurance costs had led some people to go without coverage or carry less coverage than they wanted. Many insured homeowners also said premiums had increased more than they expected.
This creates a difficult financial trade-off. Reducing coverage may lower the immediate premium, but it can leave a household exposed to substantial losses after a covered disaster or other insured event.
Homeowners should compare policies carefully, review deductibles and exclusions, and confirm whether their coverage reflects the cost of rebuilding the property rather than simply its market value.
3. Property taxes and local fees
Property taxes can increase even when a homeowner’s mortgage payment remains unchanged, particularly when local assessments, tax rates, or applicable levies change.
The amount owed depends on local rules, the property’s assessed value, and available exemptions. Some homeowners may qualify for relief based on age, disability, income, veteran status, or other criteria, depending on the state and locality.
Homeowners association and condominium fees can create additional costs. These charges may fund shared amenities, landscaping, building maintenance, insurance for common areas, and reserve funds for major repairs.
In some communities, associations may also impose special assessments when existing reserves are insufficient to cover substantial work. Buyers considering a condominium or property in a planned community should examine the association’s budget, reserve funding, meeting records, and history of special assessments when possible.
4. Utilities and energy efficiency
Electricity, natural gas, water, and sewer bills are recurring expenses that can influence the affordability of a home.
Older windows, inadequate insulation, inefficient heating and cooling systems, and air leaks can increase energy consumption. Water leaks and inefficient appliances can also add to household costs.
Improvements such as sealing air leaks, upgrading insulation, servicing HVAC equipment, and installing more efficient appliances may reduce ongoing expenses. However, the upfront cost of these improvements can be substantial, and the financial payback depends on the home’s condition, local energy prices, and how much energy the upgrade saves.
Homeowners should compare expected savings with installation and financing costs rather than assuming that every energy-efficient upgrade will pay for itself quickly.
Why Older Homes Can Be More Expensive to Maintain
Older properties often have features that require more frequent attention, particularly when major systems have not been updated or previous maintenance has been deferred.
Roofing, plumbing, electrical systems, foundations, windows, and heating and cooling equipment all have different lifespans. When several components approach the end of their useful lives at roughly the same time, repair costs can accumulate quickly.
Research from Harvard’s Joint Center for Housing Studies highlights the connection between housing age and repair needs. A report discussed by the center found that 48% of owner-occupied homes built before 1940 needed at least one repair in 2024, compared with 26% of homes built in 2000 or later. Older homes also had higher average estimated repair costs in that analysis.
This does not mean every older home is expensive or every newer home is trouble-free. A well-maintained older property may be in better condition than a newer house with construction defects or neglected systems.
The important factor is the property’s actual condition and maintenance history.
Before buying a home, prospective owners should consider a professional inspection and ask about the age and condition of major components. Depending on the property, additional inspections for pests, sewer lines, foundations, roofs, or other specialized concerns may be worthwhile.
An inspection cannot predict every future failure, but it can help buyers identify visible problems and estimate which repairs may need attention first.
How Rising Maintenance Costs Are Changing Homeowner Decisions
Homeowners are postponing some renovations
When essential expenses increase, many households reconsider projects that are desirable but not urgent.
A kitchen remodel, new flooring, landscaping improvements, or cosmetic bathroom renovation may be delayed while the owner addresses a leaking roof or a malfunctioning heating system.
Angi’s 2026 homeowner survey reported that many households were prioritizing repairs and preventative maintenance over discretionary projects as material and labor costs increased. Its findings also indicated that a substantial share of homeowners who hired professionals exceeded their original project budgets.
This shift can affect contractors and home improvement businesses because customers may reduce the number of projects they undertake while spending more on the work they cannot postpone.
For homeowners, the challenge is deciding which projects are essential, which can wait, and which improvements might reduce future operating costs.
More families are choosing to stay in their current homes
Moving can involve real estate commissions, closing costs, moving services, higher mortgage rates, and potentially higher property taxes or insurance premiums.
For households that secured a relatively low mortgage rate in previous years, moving to another property may significantly increase monthly borrowing costs. Staying in the current home can therefore appear more attractive, even when maintenance expenses are rising.
However, remaining in a home is not automatically the cheapest option. A property with major structural issues, high energy costs, or expensive maintenance requirements may eventually become financially impractical.
Homeowners should compare the expected cost of staying, including future repairs and modifications, with the total cost of moving to another property. That comparison should include transaction costs and ongoing expenses, not just the difference between mortgage payments.
First-time buyers are reconsidering their budgets
For prospective buyers, the gap between mortgage affordability and total homeownership affordability is becoming increasingly important.
A household may qualify for a mortgage but struggle to manage the combined costs of insurance, taxes, utilities, repairs, and everyday living expenses.
This can be particularly challenging for first-time buyers who have limited savings after paying a down payment and closing costs. A newly purchased home may require immediate work even if it appears ready to occupy.
Buyers should therefore evaluate the property’s condition and ongoing expenses before deciding how much they can afford to spend. A lower purchase price does not always translate into lower long-term costs if the home requires extensive repairs.
How Homeowners Can Prepare for Rising Maintenance Expenses
Although homeowners cannot control every repair or price increase, several practical strategies can help make expenses more manageable.
Create a dedicated home maintenance fund
A separate savings account can help households prepare for repairs without relying entirely on credit cards or personal loans.
Some financial professionals suggest budgeting a percentage of the home’s value each year for maintenance, but this is only a rough starting point. Actual costs depend on the property’s age, condition, climate, construction, and the owner’s ability to perform routine tasks.
A newer home with recently replaced systems may need a different budget from an older property with aging plumbing and roofing.
Homeowners should use inspections, maintenance records, and the estimated replacement dates of major systems to create a more realistic plan.
Prioritize preventative maintenance
Routine maintenance can help identify certain problems before they become more expensive, although it cannot prevent every failure.
Useful tasks may include:
- Inspecting the roof and gutters for visible damage.
- Checking for plumbing leaks and signs of water intrusion.
- Servicing heating and cooling systems according to manufacturer guidance.
- Testing smoke alarms and carbon monoxide detectors.
- Maintaining caulking and weatherstripping where needed.
- Checking drainage around the foundation.
- Addressing signs of pests or structural deterioration promptly.
The appropriate schedule depends on the home’s systems and local conditions. Homeowners should follow manufacturer recommendations and consult qualified professionals when work involves safety risks or specialized equipment.
Compare estimates and understand the scope of work
For significant repairs, obtaining multiple estimates can help homeowners understand prevailing prices and compare proposed solutions.
The cheapest estimate is not always the best choice. Homeowners should examine the contractor’s qualifications, insurance, references, warranty terms, materials, permits, and expected timeline.
Written estimates should explain what work will be completed, which materials are included, and how additional problems or unexpected costs will be handled.
For urgent repairs, homeowners may have less time to compare options. Maintaining a list of reputable local professionals before an emergency occurs can help reduce the pressure to make a rushed decision.
Explore assistance programs where eligible
Some households may qualify for financial assistance with urgent repairs, energy improvements, or accessibility modifications.
Depending on eligibility and location, options may include state or local housing rehabilitation programs, utility weatherization assistance, and programs administered by the U.S. Department of Energy or the U.S. Department of Agriculture’s Rural Development program.
Availability varies, and assistance may depend on income, location, property type, or the nature of the project. Homeowners should use official government resources to verify eligibility and application requirements before committing to work.
What Prospective Homebuyers Should Consider Before Purchasing
For people preparing to buy a home, the best time to evaluate maintenance costs is before signing a purchase agreement.
First, review the property’s age and condition, paying particular attention to the roof, foundation, plumbing, electrical systems, windows, and heating and cooling equipment.
Second, estimate recurring expenses. Property taxes, insurance premiums, utilities, and association fees can vary considerably between properties, even within the same region.
Third, consider the local environment. Homes in areas exposed to flooding, hurricanes, wildfires, extreme heat, or freezing temperatures may require specialized maintenance or insurance coverage.
Fourth, avoid using all available savings for the down payment and closing costs if doing so would leave the household without a financial cushion. New owners should prepare for immediate purchases, routine upkeep, and unexpected repairs.
Finally, remember that homeownership should fit within the household’s broader financial plan. A property that consumes nearly all available income may leave little room for retirement contributions, medical expenses, childcare, or other priorities.
What Americans Should Watch Through the Rest of 2026
Several developments are worth monitoring as homeowners plan their budgets for the remainder of 2026.
Insurance costs and availability: Premiums, deductibles, and coverage options may vary significantly by location and property risk. Homeowners should review renewal notices carefully and compare policies without sacrificing necessary protection.
Labor and material prices: Repair costs can change with local demand, contractor availability, supply conditions, and the type of work required. Obtaining updated estimates before beginning a project can help households plan more accurately.
Property taxes and local fees: Homeowners should monitor assessment notices, tax bills, and association budgets. Where exemptions or appeals are available, reviewing the requirements and deadlines may help eligible households manage expenses.
Maintenance and renovation priorities: As budgets remain under pressure, preventive maintenance and essential repairs may take precedence over cosmetic upgrades. Homeowners who plan projects should distinguish between work that protects the property and improvements that can reasonably be postponed.
Housing affordability: The total cost of ownership will remain an important consideration for buyers deciding whether to purchase, rent longer, or choose a different property. Mortgage rates are only one part of that calculation.
Final Thoughts
Rising home maintenance costs are changing how Americans understand the real cost of homeownership. A mortgage payment may be predictable, but repairs, insurance, taxes, utilities, and other expenses can make the overall financial commitment much larger than expected.
For longtime homeowners, these costs may require more careful budgeting and difficult decisions about which projects to complete. For first-time buyers, they reinforce the importance of looking beyond the purchase price and evaluating a property’s condition, recurring expenses, and future repair needs.
The most practical response is to plan ahead. A dedicated maintenance fund, regular inspections, preventative care, and careful contractor comparisons can help households prepare for expenses that might otherwise become financial emergencies.
Homeownership can still provide stability and long-term value, but its benefits are easier to manage when owners understand the full range of costs involved. By treating maintenance as a core part of the housing budget rather than an occasional expense, American households can make more informed decisions about buying, improving, and keeping their homes.

Emilly Correa has a degree in journalism and a postgraduate degree in Digital Marketing, specializing in Content Production for Social Media. With experience in copywriting and blog management, she combines her passion for writing with digital engagement strategies. She has worked in communications agencies and now dedicates herself to producing informative articles and trend analyses.