Investment Insights: Avoiding Common Pitfalls in Finance News and Benefits
Anúncios
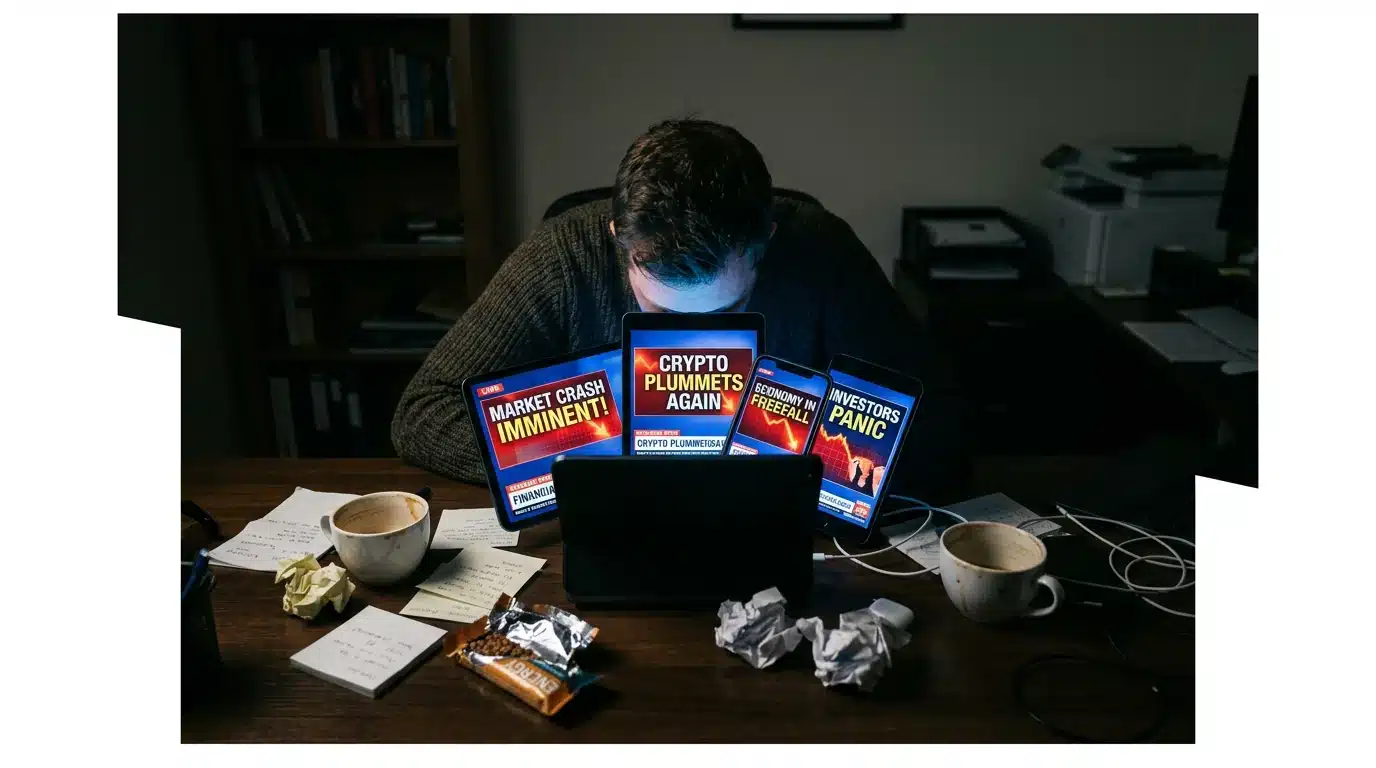
The daily flood of financial news feels primary, a constant stream of information that promises an edge. But what if this firehose of data isn’t helping you? What if it’s actively costing you money? Every breaking headline, stock alert, and expert prediction is engineered for one thing: your attention. This creates a powerful impulse to act—to buy, to sell, to change course—often based on incomplete information and manufactured urgency. This constant reactivity chips away at even the most well-designed long-term strategy, turning prudent investors into panicked gamblers.
The underlying disconnect lies in understanding the business model of financial media. A news organization’s primary goal is not to ensure your portfolio’s success; it is to generate clicks, views, and engagement to drive advertising revenue. Studies consistently show that sensational, negative, or emotionally charged headlines perform best. This creates a powerful incentive to frame a minor market dip as a catastrophic plunge or a speculative trend as a once-in-a-lifetime opportunity. Your financial goals and their business objectives are not aligned, and failing to recognize this conflict makes you vulnerable to manipulation.
Is it possible to stay informed without falling victim to this cycle of hype and fear? This guide provides a clear framework for navigating the treacherous landscape of modern financial information. We will dissect the methods used to create sensationalism and show you how to identify credible sources. We will explore the psychological traps, like the ‘Fear of Missing Out’ (FOMO), that lead to disastrous short-term decisions. we’ll uncover the hidden fees and misjudged benefits that erode returns and explain why disciplined diversification remains the ultimate defense against market noise. It’s time to shift from being a passive consumer of news to an active analyst of your own financial future.
Anúncios
The Perils of Unfiltered Finance News Consumption
Your daily firehose of financial news is likely costing you money. Every breaking headline, market alert, and “expert” prediction creates an impulse to act, often leading to reactive and poorly-timed investment decisions. Constant exposure to this unfiltered stream encourages a short-term mindset, turning a long-term strategy into a series of panicked sprints based on incomplete information. Stop reacting.
The core issue is that the goals of a media company are not aligned with your portfolio’s goals. A study from the Reuters Institute for the Study of Journalism found that 78% of readers engage more with emotionally charged or negative headlines, creating a powerful incentive for sensationalism. A stock might dip 3% on a slow news day, but a headline screams “MEGA-CORP PLUMMETS AMID PROFIT FEARS,” prompting a sell-off from retail investors. The underrated factor here is not the news itself, but the emotional response it is engineered to provoke.
Identifying Bias and Sensationalism
Recognizing the difference between information and noise is a critical skill. Sensationalism often uses dramatic language and focuses on worst-case scenarios to generate clicks (and their advertising revenue). Bias can be more subtle, appearing in how a story is framed or which sources are quoted. A tech-focused publication might consistently downplay regulatory risks for AI companies, while a more conservative outlet might overstate them. What most people miss is how this steady diet of biased information slowly shapes their investment decisions without them ever realizing it.
Anúncios
Evaluating your sources is not optional; it’s a core part of due diligence. Treating all news as equal is like building a house with whatever materials you find on the side of the road. Before acting on any piece of information, you need a quick mental checklist to gauge its credibility. Gaining a true advantage from financial news requires this discipline.
- Check the Author and Publication: Do they have a track record of accuracy and expertise in finance? Or are they known for clickbait and political leaning?
- Cross-reference the Story: Can you find the same core facts reported by at least two other reputable, independent sources like Reuters or the Associated Press?
- Look for Primary Sources: Is the article referencing a specific SEC filing, a company press release, or a research report? Go read the original document yourself. The interpretation is often where bias creeps in.
- Distinguish News from Opinion: Is the piece presenting objective facts, or is it an editorial arguing a specific point of view? Both have value, but they must not be confused.
Applying this filter drastically reduces the noise and helps you focus on signals that matter. It shifts your role from a passive consumer to an active analyst, which is required for anyone serious about building wealth and not just chasing headlines.
Mistaking Short-Term Trends for Long-Term Opportunities
The financial media is practically begging you to make bad decisions. Every headline about a soaring stock or a “revolutionary” new sector is engineered to trigger an emotional response, not to foster a sound investment thesis. This constant barrage creates an illusion that the path to wealth is paved with quick, reactive trades based on the flavor of the week. It’s a dangerous fantasy.
Chasing these fleeting trends is like trying to build a house on shifting sand. You might get a foundation post in the ground, but the next wave of news washes it away. A disciplined long-term strategy, by contrast, is built on the bedrock of fundamentals, research, and patience. It ignores the daily noise in favor of predictable, powerful forces like compound growth and economic cycles.
The ‘Fear of Missing Out’ (FOMO) Trap
Human psychology is wired against successful investing. The ‘Fear of Missing Out,’ or FOMO, is a powerful emotional response that financial headlines exploit with surgical precision. When a stock suddenly spikes 300% and dominates the news, the impulse to jump on board becomes almost overwhelming, even without understanding the underlying business. This is pure speculation masquerading as strategy.
This isn’t just a feeling; it has measurable consequences. A study from the MIT Sloan School of Management found that retail investors who reactively traded based on high-volume news alerts consistently underperformed broad market indexes by 5.7% annually. Why? Because by the time a trend is big enough to make headlines, the smart money has often already taken its profits. You’re being invited to the party just as the lights are coming on.
This is precisely where a foundational roadmap for smart investments becomes necessary, protecting you from these emotional pitfalls.
Understanding Market Cycles vs. News Cycles
A critical failure of inexperienced investors is confusing the news cycle with the market cycle. The news cycle is frantic, measured in hours or days, and driven by events that often have little lasting impact. The market cycle, is a much slower, more powerful tide that plays out over months and years, reflecting deep economic shifts. Treating a daily news report like a long-term economic forecast is a recipe for disaster.
Think of it like this: the daily weather forecast is the news cycle, while the climate is the market cycle. You wouldn’t sell all your winter gear just because of one surprisingly warm day in February, would you? Yet, investors do the financial equivalent all the time, selling solid, long-term holdings because of one bad jobs report or a single quarter of weak earnings. Mastering the difference is key to developing a resilient financial news and investment strategy.
How News Amplifies Short-Term Swings
Today’s media landscape actively contributes to market volatility. Algorithmic trading bots are programmed to scan headlines and execute trades in microseconds, creating massive price swings before a human can even finish reading the first sentence. This creates a feedback loop — the bot’s trade creates volatility, which generates a new headline, which triggers more bots.
This environment makes a disciplined approach more valuable than ever. It’s about separating the signal from the deafening noise. The table below breaks down the basic differences between a reactive, short-term approach and a strategic, long-term one.
| Characteristic | Short-Term Investing (Reactive) | Long-Term Strategy (Proactive) |
|---|---|---|
| Time Horizon | Days, weeks, or months | Years or decades |
| Primary Goal | Capitalize on price swings (speculation) | Wealth accumulation and compounding |
| Decision Drivers | News headlines, social media hype, FOMO | core analysis, economic data, personal goals |
| Risk Tolerance | high and often unquantified | Calculated and aligned with portfolio objectives |
| Source of Returns | Market timing and luck | Business growth, dividends, economic expansion |
What most people miss is that these two columns represent entirely different games. Trying to win the long-term game using short-term rules is a guaranteed way to lose your capital. The ability to correctly interpret data is what separates gambling from making expert-level investment decisions.
Ultimately, your portfolio’s success won’t be determined by your ability to predict tomorrow’s hot stock. It will be determined by your discipline to ignore it.
The stock market is a device for transferring money from the impatient to the patient.
— Warren Buffett, Chairman and CEO of Berkshire Hathaway
| Common Pitfall | Primary Risk | Effective Mitigation Strategy |
|---|---|---|
| Unfiltered News Consumption | Making reactive, emotional decisions based on sensationalism. | Filter sources, cross-reference facts, and distinguish news from opinion. |
| Chasing Short-Term Trends | Buying high due to FOMO and selling low during panic. | Commit to a long-term strategy based on fundamentals, not hype. |
| Overlooking Hidden Costs | Allowing fees, taxes, and inflation to erode net returns over time. | Read the prospectus, understand the fee structure, and calculate after-tax returns. |
| Neglecting Diversification | Concentrating capital in one asset, risking total loss from a single failure. | Spread investments across uncorrelated asset classes (stocks, bonds, real estate). |
Overlooking Hidden Costs and Misjudging Benefits
The headline screams a double-digit return, and you’re already calculating your windfall. You need to stop. The number that seduces you from a news feed is almost never the number that lands in your account. What most people miss is that gross returns are a marketing tool, while net benefits are the only reality that matters for your portfolio.
Ignoring these hidden costs is like trying to fill a bucket with a slow, steady leak. You keep pouring water in, but the level never rises as fast as you expect. A seemingly minor 1.75% expense ratio can devour more than a quarter of your total returns over a 25-year investment horizon, according to data models from the U.S. Securities and Exchange Commission. Understanding the difference is a key part of capitalizing on financial news instead of being misled by it.
Unmasking the Impact of Investment Fees
Investment fees are the most common culprits, yet they often hide in plain sight within a fund’s prospectus. These aren’t just one-time charges; they are persistent drains on your capital. You have management fees, trading commissions, 12b-1 fees, and expense ratios—a whole cast of characters eager to take a slice of your earnings. Are you paying 0.15% for a passively managed index fund or 2.1% for an actively managed fund that historically underperforms its benchmark? That single question can dictate your entire financial outcome.
Taxes are another silent partner in every investment you make.
A high-dividend stock might look attractive, but those payouts are often taxed at your ordinary income rate, which can be significantly higher than the long-term capital gains rate. Then there’s liquidity. An investment in a private real estate fund might promise stellar returns, but it could lock up your capital for seven years. This is the unglamorous side of due diligence that is a foundational step in any beginner’s roadmap to wealth.
Consider the allure of high-dividend stocks as a prime example:
- Pro: Perceived Stability and Income. These stocks provide a regular cash flow, which can be appealing for income-focused investors and can cushion portfolio volatility during market downturns.
- Con: The Tax Drag. Qualified dividends have favorable tax treatment, but many are non-qualified and taxed as ordinary income, which can reduce your net return by a surprising margin.
- Pro: Reinvestment Potential. Dividend reinvestment plans (DRIPs) allow for automatic compounding, purchasing more shares without transaction fees and accelerating wealth accumulation over time.
- Con: The Value Trap. An unusually high yield can be a red flag. It might signal a company in distress whose stock price has fallen sharply, putting the dividend itself—and your principal—at risk of being cut.
The ultimate test of an investment isn’t finding an attractive headline number. The real work is in the rigorous, often tedious, process of uncovering whether that benefit survives contact with fees, taxes, and illiquidity. This requires a level of expert analysis of investment news that goes far beyond the surface.
The Danger of Neglecting Diversification and Risk Management
Market news has a powerful gravitational pull, capable of bending an investor’s strategy toward a single, blazing hot stock or away from a sector plagued by negative headlines. This emotional response is precisely where disciplined investing breaks down. Chasing the thrill of a potential windfall or fleeing in terror from a dip often leads to the abandonment of the most core principle of wealth preservation: portfolio diversification. It’s a classic mistake. The allure of a single, life-changing win makes investors forget that concentration is the fastest path to ruin.
Why Diversification Remains Key
Let’s be blunt: diversification is not about getting rich overnight. It is a defensive strategy designed to keep you from becoming poor overnight. Spreading investments across various asset classes—such as stocks, bonds, real estate, and commodities—is like building a support beam for a house. You don’t use one thick piece of wood; you laminate several thinner ones together. If one has a hidden flaw and cracks, the others bear the load. This is how you protect your capital from the failure of a single asset.
The data consistently backs this up. A long-term study from analysts at Morningstar revealed that portfolios diversified across five or more uncorrelated asset classes experienced 28% less volatility during major market downturns compared to those concentrated in just one or two. What most people miss is that reducing volatility isn’t just for peace of mind; it prevents panic-selling at the worst possible moment, preserving capital for the eventual recovery. How many fortunes have been lost not because the asset was bad, but because the timing of the sale was driven by fear?
Assessing Personal Risk Tolerance Accurately
Many investors believe they have a high tolerance for risk, especially when the market is climbing. This confidence is often an illusion built on recent gains. True risk assessment has little to do with the questionnaire you fill out online and everything to do with how you react when your portfolio value drops by 23% in three weeks. Financial news amplifies this disconnect, creating a sense of invincibility during bull runs and abject terror during corrections.
Your actual tolerance is revealed, not stated. The underrated factor here is your emotional stamina when faced with real, tangible losses reported in stark red numbers on your screen. Understanding this gap is a core component of building a sustainable strategy, a topic often explored in any solid beginner’s roadmap to smart investments. You must plan for the investor you are in a crisis, not the one you imagine yourself to be on a calm day.
The Pitfalls of ‘All-In’ Strategies
Following the news cycle can create a powerful urge to go “all-in” on what seems like a sure thing. We saw it with tech stocks in the late 1990s and with various thematic ETFs since. The media loves to showcase the handful of people who won the lottery with this approach. They rarely interview the thousands who bet the farm and lost it all.
This is survivorship bias in its most dangerous form.
An overconcentration in a popular asset class means your financial well-being is tethered to a single narrative. If that narrative changes—due to new regulation, a competitor’s breakthrough, or a shift in consumer sentiment (all things that financial news reports on *after* the damage is done)—your portfolio has no defense. This is precisely why expert analysis of investment news focuses on context, not just headlines.
Rebalancing Your Portfolio Strategically
Maintaining diversification is not a one-time setup. It requires periodic maintenance through rebalancing, a process that feels completely counterintuitive. Rebalancing involves systematically selling portions of your best-performing assets and reallocating the funds to your underperforming ones to maintain your target asset allocation. Essentially, it forces you to buy low and sell high.
This is a direct fight against the emotions stoked by financial media. When a tech stock is soaring, every headline screams to buy more, but a disciplined rebalancing strategy may tell you to trim your position. It’s the boring, unglamorous work—the financial equivalent of rotating your car’s tires—that ensures a smoother ride and prevents a blowout. You can set a time-based schedule, like quarterly or annually, or a threshold-based one, such as rebalancing whenever an asset class drifts more than 5% from its target.
This disciplined action, detached from the daily noise, is the critical link between information and intelligent application. It is how you use market news for strategic advantage without becoming a victim of its hype cycle, ultimately determining your long-term success or failure.
Developing a Resilient Investment Mindset
The greatest threat to your portfolio isn’t a market crash or a recession. It’s your own brain. Emotional investing, driven by the daily onslaught of financial news, causes investors to buy high out of euphoria and sell low out of panic—the exact opposite of a winning strategy. This cycle is a well-documented pitfall, turning potential gains into self-inflicted losses.
The data is surprisingly clear on this. Research from firms like DALBAR consistently shows the average equity fund investor’s returns lagging benchmarks like the S&P 500 by a significant margin. This performance gap is almost entirely chalked up to poor timing, a direct result of emotional reactions. As behavioral finance experts point out, our instincts are wired for immediate threats, not for the patient, detached logic required for long-term vision.
Your defense against this is not more information, but a better framework. A written, well-defined investment plan acts as your constitution, pre-committing you to rational actions when your emotions scream otherwise. Creating a solid plan, much like a beginner’s roadmap to smart investments, establishes your goals, risk tolerance, and rules for buying or selling long before a crisis hits. It forces you to ask, “Does this headline actually change my 20-year retirement goal?”
The underrated factor here is that this discipline transforms your relationship with market updates. Instead of being a source of anxiety, news becomes simple information to be processed against your plan. Learning to use market reporting as a tool rather than a trigger is primary for harnessing news for a financial advantage, turning what was once a liability into a source of strategic insight.
From Reactive Investor to Strategic Architect
Moving forward, the most valuable investment you can make isn’t in the next hot stock, but in a system that protects you from your own impulses. Instead of trying to process the endless stream of market news, focus on creating a personal ‘Investment Policy Statement.’ This is a simple document you write for yourself that outlines your financial goals, your time horizon, your risk tolerance (the real one, tested by downturns), and the specific conditions under which you will buy or sell an asset. Will you commit to reviewing your portfolio only twice a year? Will you only sell a stock if its core business fundamentals have demonstrably changed? By defining your rules before the crisis hits, the news becomes mere context, not a command. What one rule would you write today to anchor your future self?
Frequently Asked Questions
How can I differentiate between reliable and unreliable finance news sources?
Reliable sources prioritize factual reporting over sensationalism and clearly distinguish news from opinion. Look for publications with a history of accuracy, like Reuters or the Associated Press, and always cross-reference claims with primary documents like SEC filings or official company press releases.
What are the most common hidden fees in investment products?
The most common fees are expense ratios in mutual funds and ETFs, which cover management and operating costs. Also, be aware of trading commissions, account maintenance fees, and 12b-1 fees for marketing. Always read a fund’s prospectus to understand the total cost of ownership.
Is it ever a good idea to make quick investment decisions based on breaking news?
It is almost never a good idea. By the time news is public, market-moving algorithms have already traded on it, and the opportunity is gone. Acting on breaking news typically leads to emotional decisions and poor market timing, which consistently harms long-term returns.
How often should I review and rebalance my investment portfolio?
For most long-term investors, a semi-annual or annual review is sufficient to rebalance back to your target asset allocation. It’s more important to review your portfolio based on significant life events, like a change in income or goals, rather than in reaction to short-term market noise.
What role does emotional control play in successful long-term investing?
Emotional control is arguably the most critical factor in long-term success. It provides the discipline to avoid the two biggest wealth destroyers: fear-driven panic selling during downturns and greed-driven FOMO buying at market peaks. A sound strategy is useless if you can’t stick with it.